Minimum Down Payment on a $500,000 House in Albuquerque, New Mexico
What is the minimum down payment on a $500,000 house in Albuquerque?
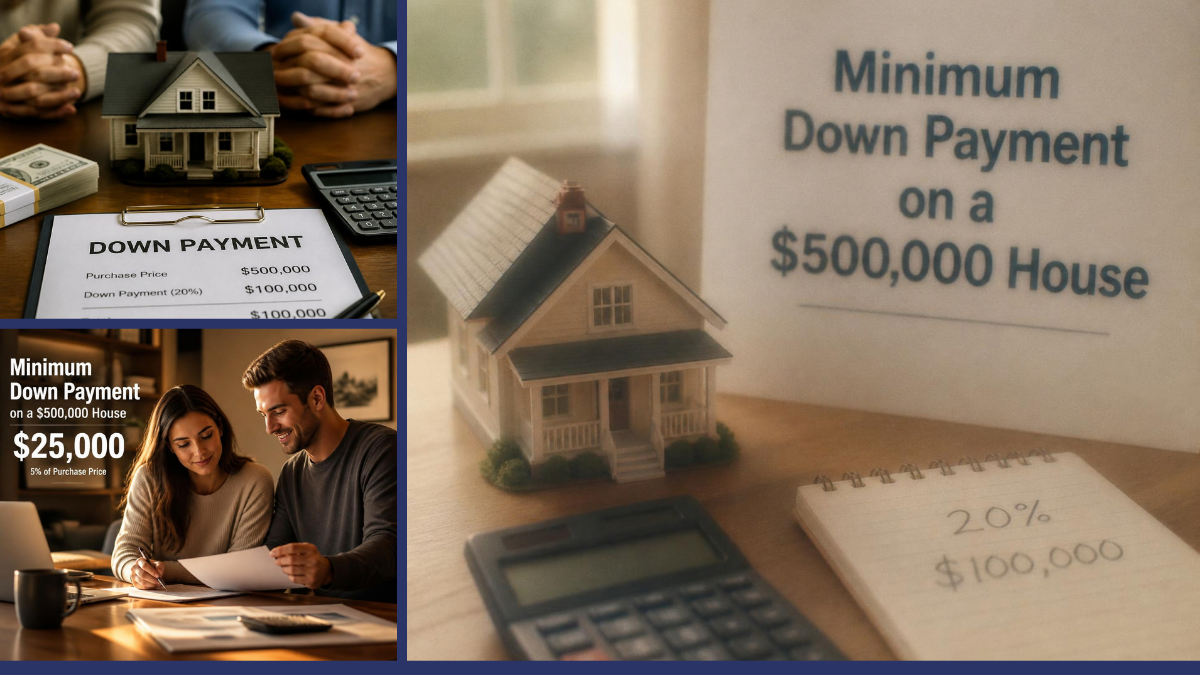
The absolute minimum is $0 if you qualify for a VA or USDA loan. Otherwise, you could pay as little as 3% ($15,000) with a conventional program or 3.5% ($17,500) with FHA, depending on your credit score and eligibility.
Why This Matters Right Now for Albuquerque Homebuyers
If you have been through a foreclosure, short sale, or bankruptcy, you might assume that buying a home again is out of reach. We hear this concern constantly from homeowners across Albuquerque who are rebuilding. The truth is, homeownership is absolutely possible again, but the down payment you need depends entirely on where you are in your financial recovery.
Here in Bernalillo County, a $500,000 purchase falls comfortably within both the 2026 conforming loan limit of $832,750 (as of January 2026, per FHFA) and the 2026 FHA loan limit floor of $541,287 (as of January 2026, per HUD). That means you have access to the full range of low-down-payment and zero-down-payment programs. The difference between $0 down and $100,000 down is not just a number on a page. It determines whether you can make a move this year or whether you need to keep saving. Let us walk through every option so you can figure out exactly where you stand.
Zero Down Payment Options Available in Albuquerque
Here is what we tell our clients right away: the absolute minimum down payment for a $500,000 house is $0 if you qualify for a VA loan or a USDA loan. That is not a typo, and it is not a gimmick. These are real, federally backed programs that we work with regularly across New Mexico.
VA Loans: For Those Who Have Served
If you are an eligible veteran, active-duty service member, or surviving spouse, a VA loan lets you purchase a $500,000 home in Albuquerque with zero money down (as of January 2026, per HUD). For distressed homeowners who also happen to be veterans, this can be a genuine lifeline. Your military service earned you this benefit.
USDA Loans: Location and Income Matter
USDA loans also offer 0% down, but eligibility depends on the specific property location and your household income (as of January 2026, per HUD). Not every neighborhood in Albuquerque qualifies. Some of the more suburban and outlying areas around the metro may be eligible, while properties in more densely developed parts of the metro may not qualify. We always recommend checking USDA eligibility maps for the specific address you are considering. If your income falls within the program limits and the property qualifies, this is one of the most powerful tools available.
With 12 years of experience and over 250 transactions closed across the Albuquerque market, we have helped buyers navigate both of these programs many times. The key is knowing which program fits your situation before you start shopping.
FHA Down Payments on a $500,000 Home in Albuquerque
For many buyers recovering from financial hardship, FHA loans are the most accessible path forward. Your credit score determines the minimum you need.
Credit Score 580 or Above: 3.5% Down
If your credit score is 580 or higher, FHA requires a minimum down payment of 3.5% (as of January 2026, per HUD). On a $500,000 home, that works out to $17,500. Since the 2026 FHA loan limit floor for Bernalillo County is $541,287, your $500,000 purchase is well within program limits.
Keep in mind that FHA also requires both an upfront mortgage insurance premium and an annual mortgage insurance premium. These costs add to your monthly payment and your cash needed at closing, so you should factor them into your total budget, not just the down payment number.
Credit Score 500 to 579: 10% Down
What if your credit score is still recovering and sits between 500 and 579? You are not locked out of FHA, but the minimum jumps to 10% (as of January 2026, per HUD). On a $500,000 house, that means $50,000. That is a significant difference, and it is one of the strongest reasons to work on your credit score before you start the buying process. If you are in the 500 to 579 range, a conversation with a qualified lender about credit repair strategies could be the most valuable step you take.
Conventional Loan Down Payments in the Albuquerque Market
Conventional loans backed by Fannie Mae and Freddie Mac offer their own low-down-payment options, and they work well for a $500,000 home since the 2026 conforming loan limit is $832,750 (as of January 2026, per FHFA).
3% Down for Eligible Buyers
Programs like Fannie Mae's HomeReady and Freddie Mac's Home Possible allow as little as 3% down for qualifying first-time or lower-income buyers. On a $500,000 purchase, that is $15,000, making this the lowest non-zero down payment option available. You will need to meet specific income and eligibility requirements, and private mortgage insurance (PMI) is required until you reach 20% equity.
5% Down: The Standard Conventional Minimum
If you are a repeat buyer who does not qualify for a 3% program, the standard conventional minimum is 5% (as of January 2026, per FHFA). That means $25,000 on a $500,000 home. PMI still applies until your loan-to-value ratio reaches 80%.
20% Down: The PMI Elimination Milestone
Putting 20% down, which is $100,000 on a $500,000 house, eliminates the requirement for private mortgage insurance entirely (as of January 2026, per FHFA). For most buyers rebuilding after financial hardship, this is a long-term goal rather than something you need right now. We frame it as a milestone, not a barrier. You do not need $100,000 to buy a home in Albuquerque. But understanding this threshold helps you plan for the future.
So what does all of this actually look like when you compare your options side by side?
Your Down Payment Comparison for a $500,000 Albuquerque Home
Let us break down the real dollar amounts so you can see exactly what each program requires:
- VA Loan (0% down): $0 down payment. Available to eligible veterans, active-duty service members, and surviving spouses.
- USDA Loan (0% down): $0 down payment. Property must be in an eligible area, and household income limits apply.
- Conventional 3% (HomeReady/Home Possible): $15,000 down payment. Must meet first-time buyer or income eligibility requirements. PMI required.
- FHA 3.5% (credit score 580+): $17,500 down payment. Upfront and annual mortgage insurance premiums apply.
- Conventional 5% (standard): $25,000 down payment. Available to repeat buyers. PMI required.
- FHA 10% (credit score 500-579): $50,000 down payment. Upfront and annual mortgage insurance premiums apply.
- Conventional 20%: $100,000 down payment. No PMI required.
The spread between the lowest and highest option here is $100,000. That is not a small detail. It is the difference between buying a home this year and waiting several more years to save. The right program for you depends on your military service, your credit score, your income, and the specific Albuquerque neighborhood where you want to live.
What Distressed Homeowners in Albuquerque Need to Know About Eligibility
If you have experienced a foreclosure, short sale, or bankruptcy, the down payment percentages above still apply, but you may face mandatory waiting periods before you qualify for certain loan programs. Each program, whether VA, USDA, FHA, or conventional, has its own timeline and its own provisions for extenuating circumstances.
We specialize in foreclosures and work with buyers navigating exactly these situations. What we always tell our clients is this: do not assume you are disqualified. The waiting periods exist, but they are finite, and some programs offer shorter timelines if you can document extenuating circumstances.
The practical impact is that the "minimum" down payment for your situation is not just about the loan program's rules. It is about which programs you are currently eligible for based on your credit recovery timeline. The specific waiting period that applies to your situation depends on the loan program, the type of hardship event, and whether extenuating circumstances can be documented — a qualified lender can tell you exactly which programs you are eligible for right now.
With 20 five-star reviews from past clients and a perfect 5/5 average rating, we have built our reputation on walking buyers through exactly these kinds of situations with clarity and patience. As one of our clients shared: "Vinay was absolutely fantastic, explained everything taking me from start to finish. No question unanswered."
Frequently Asked Questions
Can I buy a $500,000 house in Albuquerque with no money down?
Yes, if you qualify for a VA loan as an eligible veteran, active-duty service member, or surviving spouse, or a USDA loan for eligible property locations and income levels. Both programs allow 0% down (as of January 2026, per HUD). Not every Albuquerque location qualifies for USDA, so you will need to verify the specific address.
What is the lowest down payment for FHA on a $500,000 home?
With a credit score of 580 or above, FHA requires a minimum of 3.5%, which is $17,500 on a $500,000 purchase (as of January 2026, per HUD). If your score falls between 500 and 579, the minimum increases to 10%, or $50,000.
How much is 3% down on a $500,000 house?
Three percent of $500,000 is $15,000. This option is available through conventional programs like Fannie Mae HomeReady and Freddie Mac Home Possible for qualifying first-time or lower-income buyers (as of January 2026, per FHFA). PMI will be required.
Does the down payment amount affect my monthly mortgage payment?
Absolutely. A larger down payment means a smaller loan balance, which lowers your monthly principal and interest payment. It can also eliminate or reduce mortgage insurance costs, which further reduces what you owe each month.
Can I use gift funds for my down payment in New Mexico?
Many loan programs allow gift funds from family members or other approved sources for part or all of the down payment. Each program has specific documentation requirements. Your lender will need a gift letter and proof that the funds are truly a gift, not a loan.
Is the down payment the only upfront cost when buying in Albuquerque?
No. You will also need to budget for closing costs, which typically include lender fees, title insurance, appraisal fees, escrow deposits, and prepaid items like homeowners insurance and property taxes. These can add several thousand dollars beyond your down payment.
How long after a foreclosure can I get an FHA loan?
FHA generally has specific waiting periods following a foreclosure, and those timelines may be shorter if you can demonstrate extenuating circumstances. The exact timing depends on the type of event and your individual situation, so we recommend discussing your specific case with a qualified lender.
What credit score do I need for the lowest conventional down payment?
Conventional 3% down programs have credit score requirements that vary by lender and program — a qualified lender can confirm whether you meet the threshold for HomeReady or Home Possible. Higher scores generally give you access to better rates and lower PMI costs.
Can I buy a home in Albuquerque while still recovering financially?
Yes.
Should I wait to save 20% before buying a $500,000 home?
Not necessarily. While 20% down ($100,000) eliminates PMI, waiting years to save that amount means paying rent instead of building equity. For many Albuquerque buyers, a smaller down payment with mortgage insurance is a smarter financial move than delaying homeownership indefinitely.
The Bottom Line
You do not need $100,000 or even $25,000 to buy a $500,000 home in Albuquerque. Depending on your eligibility, you could pay as little as $0 with a VA or USDA loan, $15,000 with a conventional 3% program, or $17,500 with FHA. The right answer depends on your credit score, your military service history, and where you are in your financial recovery.
As Top-Producing Realtors recognized in the top 5% in 2023 and 2024, we have spent 12 years helping Albuquerque buyers navigate exactly these decisions. Whether you are rebuilding after a difficult financial chapter or simply trying to figure out the smartest way to get into a home, we are here to walk you through it step by step. Reach out to The Rodgers Neighborhood Real Estate Group at 505-417-2733 or visit us at 4800 Juan Tabo Blvd NE Ste D, Albuquerque NM 87111. Your next chapter starts with knowing your options, and now you do.
Categories
- All Blogs (361)
- 2026 & Beyond for Real Estate (255)
- Doctors and Nurses looking for homes in NM (4)
- Guide to buying a home in NM (159)
- Health Care Heros (7)
- Home Upgrades (42)
- Jenn & Vinay your Local Real Estate Experts! (124)
- Moving to Albuquerque (138)
- Neighborhoods in Albuquerque NM (94)
- Rent or Own (2)
- Sellers Questions for Selling homes (2)
Recent Posts
GET MORE INFORMATION